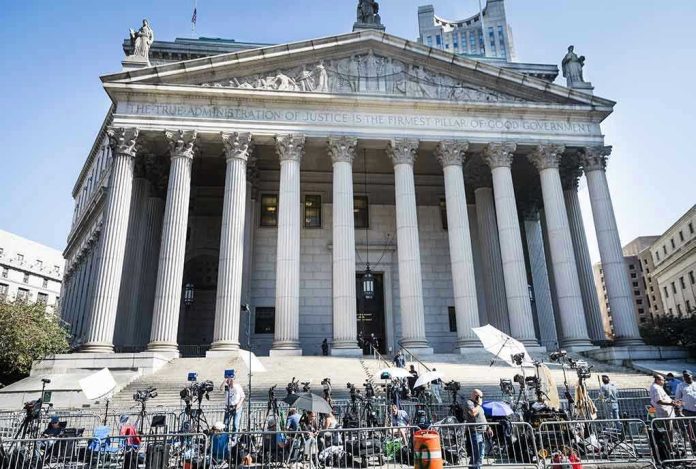
The Supreme Court will decide whether a 160-year-old home-distilling ban is a valid tool of federal tax enforcement or an unconstitutional reach into Americans’ homes.
Story Snapshot
- President Trump’s Department of Justice asked the Court to uphold the ban as a tax-enforcement measure.
- The Fifth Circuit struck the ban; the Sixth Circuit upheld it, forcing a Supreme Court showdown.
- The law dates to 1868 and forbids distilling in a dwelling or attached structure.
- Opponents argue the ban “taxes nothing” and polices private conduct beyond federal power.
What the administration told the Court, in plain terms
The Department of Justice framed the case around Congress’s taxing power and the Necessary and Proper Clause. It argued a rule can be “convenient” or “useful” to carry out a listed power and still be constitutional. The brief said home distilling hides activity from inspection and makes tax evasion easier, so Congress barred stills in dwellings and connected spaces to protect the excise tax on spirits. That pitch bets on a long tradition of allowing practical tools to enforce taxes.
The government also leaned on history. It noted the location rule has stood for about 160 years and works with criminal penalties to deter evasion. Congress chose a bright-line rule rather than play cat-and-mouse at countless front doors. The brief ties that structure to a simple idea: inspectors can police bonded, commercial sites far better than kitchens and garages, which means a location ban keeps tax compliance workable.
Why this case is at the Supreme Court now
A direct split forced review. The United States Court of Appeals for the Fifth Circuit said the home-location ban exceeds Congress’s powers. It reasoned the provisions “tax nothing” and stand apart from rules that actually collect revenue. In contrast, the United States Court of Appeals for the Sixth Circuit upheld the scheme. The Supreme Court granted review in Department of Justice v. McNutt to say which view tracks the Constitution and the Court’s Necessary and Proper precedents.
The grant raises the stakes well beyond whiskey. The Court will test the line between functional federal tools that help collect taxes and a backdoor police power inside the home. Conservative readers should watch for a clear limiting principle. If the administration’s view prevails, the opinion should mark where “useful” ends and “too far” begins. If McNutt wins, the Court will likely demand a tighter, revenue-facing nexus for any incidental rule.
What McNutt and his supporters argue the Court should reject
McNutt’s brief says a total ban on home distilling does not raise revenue and thus cannot rest on the taxing power. He argues Congress cannot forbid private, in-home conduct just because, somewhere down the line, taxes might apply. His team points to tools that actually collect or track tax, like labels, stamps, and measuring requirements, as the proper means. They say the government’s approach strips citizens of the choice to comply and pay the tax at all.
The US Supreme Court agreed on October 19 to decide the legality of an 1868 law that banned the home distilling of liquor.
For more top news, subscribe to The Daily Docket: https://t.co/aq1ioam3fY pic.twitter.com/QS09qeTBTa
— Reuters Legal (@ReutersLegal) October 20, 2026
That side also warns about a slippery slope. If “it helps taxes” is enough, then almost any in-home activity that could be taxed might be banned. That concern fits a classic federalism theme. States handle health, safety, and moral rules at home. The federal government taxes and regulates interstate markets. On the record presented, their argument claims the home-location ban polices behavior first and taxes second, flipping that order in a way the Constitution does not allow.
How a conservative, common-sense Court could thread the needle
The Court can honor both enforcement reality and constitutional limits. A strong middle path would ask the government to show a tight, evidence-backed link between the home ban and tax collection—not theory, but function. If the Justice Department proves that inspections fail in dwellings and that lesser tools do not work, the ban looks like a classic means to execute the taxing power. Without that proof, the rule risks looking like a national police measure.
Here, the administration has a coherent mechanism—concealment at home thwarts inspections and invites evasion. The law’s age and structure support that logic. But the Fifth Circuit’s “taxes nothing” critique hits a nerve. The Supreme Court’s answer will likely turn on how it reads “plainly adapted” to tax collection under its Necessary and Proper cases and the specific record it trusts in this dispute.
What to watch for when arguments land
Expect questions about real-world enforcement, not just theory. Expect probing on why a blanket home ban beats licensing, registration, or production caps. Expect a demand for a limiting principle. A decision that upholds the law will likely set guardrails to prevent federal overreach into the home. A decision that strikes it down will probably sketch a roadmap for tax-focused alternatives that stay within constitutional lanes while still protecting revenue.
Sources:
reason.com, justice.gov, washingtonexaminer.com